
Appraisal Comps: What Lenders Actually Count on a DSCR Loan
Appraisal comps are the closed sales an appraiser uses to back up a property's value, and they're often not the comps your agent pulled or the ones you ran yourself. Realtors and investors tend to reach for the sales that support the price they want. A lender's appraiser has to use sales that hold up in front of an underwriter. Here's how lenders look at comps, rents, recent listings and cash-out timing on a DSCR loan, and what I do when an appraisal comes in low.
What makes a sale a true comp for an appraisal?
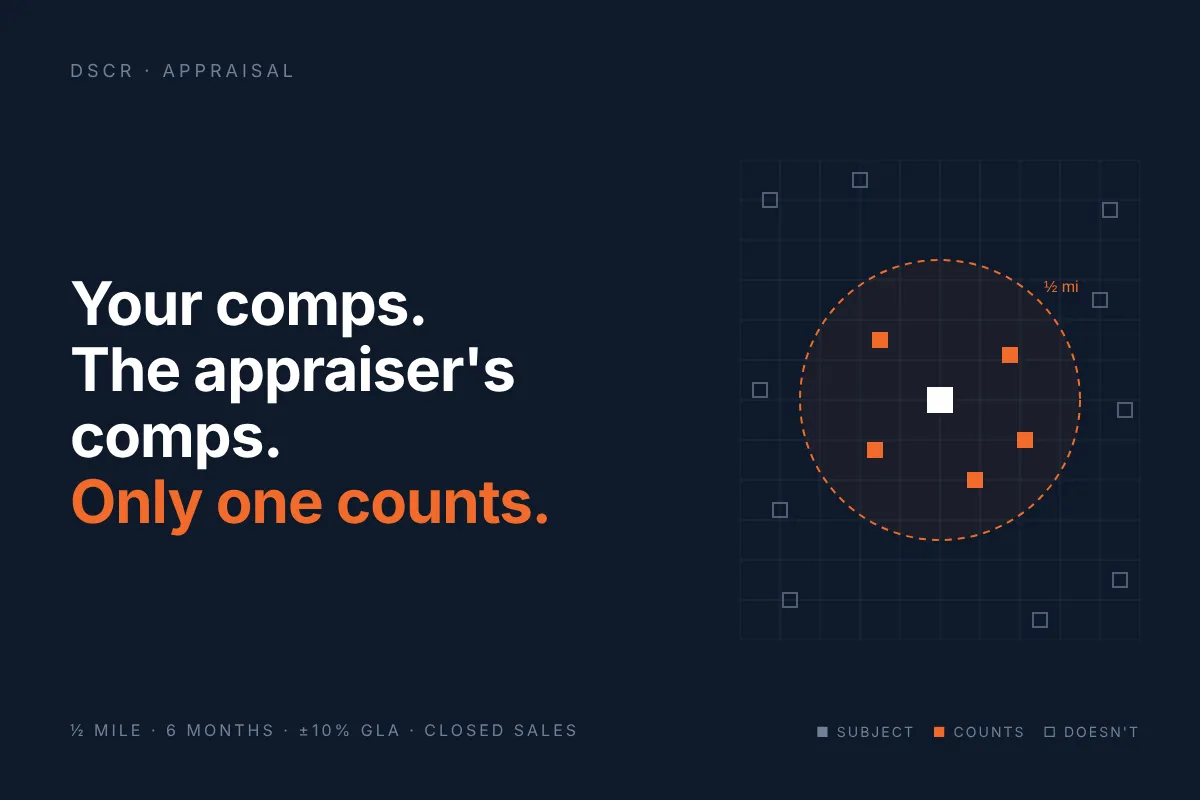
A true comp is a closed sale that's close by, recent and nearly the same house: in my experience, appraisers start within half a mile, within the last 6 months, within about 10% of the subject's living area and with like amenities. Active listings and pending sales can support the value, but the report needs at least three closed comparable sales.
"Nearly the same" covers more than square footage. Fannie Mae's comparable sales guidance lists site, room count, finished area, style and condition, and the amenities buyers pay for matter just as much: a pool, a garage, a view, lake or golf access, the same kind of HOA. A 2,000-square-foot house with a pool that sold next door isn't a clean comp for a 1,600-square-foot house without one.
Why don't the comps your agent pulled match the appraisal?
Agents and investors often reach for the highest nearby sales, active listings or renovated flips from a better street, while an appraiser is limited to closed sales they can defend line by line. Then the lender's underwriter reviews the appraisal, and on the lenders I work with, comps from outside the market area can trigger a second review of the value.
That gap is where most "the appraisal came in low" surprises come from. Here's how the two sets of comps usually differ:
Factor | Comps investors often pull | Comps a lender's appraisal uses |
|---|---|---|
Sale status | Active listings, pending sales, list prices | Closed sales; listings only as support |
Distance | Anywhere in the ZIP code | Starts within half a mile; farther only with an explanation |
Timing | Any sale that helps, even a year or more back | Starts within 6 months; older only with an explanation |
Size | "Close enough" | Within about 10% of the living area |
Features | Best-condition flips and upgraded homes | Like condition and amenities, adjusted for differences |
What happens when there aren't enough comps nearby?
The appraiser widens the search in distance and time, then explains in the report why each farther or older sale was used. The DSCR lender guides I work with fall back on Fannie Mae's rules, which call for comps closed within the last 12 months and an explanation for anything older or farther away.
One DSCR lender guide I work with, effective October 22, 2026, says comps generally shouldn't be more than 1 mile away or 12 months old, and at least two should have been listed on the MLS. In rural areas comps can be several miles out, but the appraiser can't expand the neighborhood boundaries just to reach a higher sale.
What is a 1007 and how does it set your DSCR?
A 1007 is the Single-Family Comparable Rent Schedule, an add-on to the appraisal where the appraiser compares your property to nearby rentals and gives a market rent. On a purchase, the DSCR lenders I work with use that market rent, or your lease if it's lower, and divide it by the monthly payment (principal, interest, taxes, insurance and HOA) to get your ratio.
Fannie Mae requires the 1007 whenever a one-unit investment property's rent is used to qualify, and 2–4 unit properties use the small residential income property appraisal (Form 1025) instead. On a refinance, a lease above market rent can sometimes count if you can show a few months of that higher rent actually being collected. I go deeper on how lenders count rents from the 1007, and you can check a likely number first with our DSCR rent estimate tool.
What if the property was listed for sale recently?
If it was listed in the last 6 months, most DSCR lenders I work with use the lower of the appraised value or the lowest list price from that period, and the property has to be off the market before you apply. To use the full appraised value with those lenders, you'd wait until 6 months after it came off the market, though I work with a few lenders that will use the appraised value sooner.
The logic is simple: if you were willing to sell for $400,000 last month, a lender won't lend against a $450,000 appraisal this month. Expect to explain in writing why it was listed and confirm you're keeping it. One lender guide I work with also requires a prepayment penalty or a lower maximum loan-to-value on a cash-out in this situation.
How long do you have to own a property before a cash-out refinance?
Most DSCR lenders require 6 months on title before they'll use a new appraised value for a cash-out refinance. I also work with lenders that need only 3 months, and some with no seasoning at all, which can matter a lot after a renovation.
If you bought with cash, delayed financing can let you pull money back out sooner, usually limited to what you actually put into the purchase. I cover the details in DSCR cash-out refinance and using a DSCR loan for the BRRRR method.
How much does a DSCR appraisal cost, and who orders it?
A single-family appraisal with a 1007 rent schedule runs about $700 in my experience as of October 2026, and you pay for it upfront. The lender orders it through an appraisal management company (AMC), a third party that assigns the appraiser, so neither you, your agent nor I get to pick who shows up.
That's by design. Under Fannie Mae's Appraiser Independence Requirements, mortgage brokers, loan officers and real estate agents can't select, recommend or influence the appraiser. In my experience, 2–4 unit, larger and rural properties cost more to appraise.
What can you do if the appraisal comes in low?
You can ask for a reconsideration of value (ROV), where the lender sends the appraiser better comps or corrections and asks them to take another look. It only works with real evidence: closed sales that fit the comp rules better than the ones in the report, or clear errors like wrong square footage or a missed feature.
Five federal regulators, including the CFPB, issued interagency guidance on reconsiderations of value in July 2024, so lenders have a defined process for it. Because brokers can't talk to the appraiser directly, I build the ROV myself: I go through the report, pull the comps, write up why each one is a better match, and submit it through the lender. It's hours of extra work on a file and it doesn't always move the number, but when the comps are there it can save the purchase or the cash-out.
Why does it matter which broker handles your appraisal?
Because comp reviews, listing rules and seasoning all vary by lender, and the right lender can turn one of these problems into a closed loan. A broker who knows each lender's appraisal rules, and who'll put in the work on a reconsideration of value, can keep a deal alive that a single lender would let die.
That's why I'm partnered with many DSCR lenders. A property listed 3 months ago, owned for 2 months or sitting in a neighborhood with thin sales usually has a home somewhere. Before you order an appraisal, run the numbers through our DSCR calculator so you know what value and rent the deal needs.
Not sure your comps will hold up? Send me the address and what you think it's worth. I'll tell you how a lender's appraiser is likely to see it before you spend money on an appraisal. No obligation, no hard credit pull to start.
Get Started Now or book a free consultation. Want the full program overview first? See our DSCR loans page.
About the author
Trevor Gravink is a mortgage consultant and the founder and CEO of Broker Buddy LLC, with over $200M in closed loan volume and 8 years in business. He works with real estate investors on DSCR and other investor loans. Individual NMLS #1707407, CA DRE #02117228. Connect on LinkedIn.
This article is for general education and is not a commitment to lend. Appraisal, comparable sales, rent, listing and seasoning requirements vary by lender and are subject to change; figures reflect our lender network as of October 2026. Appraisal fees vary by property and market. All loans are subject to credit approval, underwriting and an acceptable appraisal. ReBroker Buddy (Broker Buddy LLC), powered by Adaptive Mortgage Solutions, 5371 Wilshire Dr., San Diego, CA 92116, (619) 404-6637. Company NMLS #2022974, CA DRE #02126109. Equal Housing Opportunity.


