First-Time Home Buyer Loans in California
First-time home buyers in California can buy with 3% down on a conventional loan, 3.5% on an FHA loan, or 0% on a VA or USDA loan, and state programs like CalHFA’s MyHome can help cover the down payment. I compare first-time buyer programs from 40+ wholesale lenders to find you the lowest total cost.
Most first-time buyers think they need 20% down. You don’t. The right loan depends on your credit, savings and income, and on how long you plan to stay, so I’ll show you the options side by side before you write an offer.
On this page
- Who counts as a first-time home buyer?
- First-time home buyer loan options compared
- California first-time home buyer programs
- How much cash do you need to buy your first home in San Diego?
- First-time home buyer requirements
- How to buy your first home
- What homebuyers say
- What affects your first-home mortgage rate
- First-time home buyer FAQ
- More for first-time buyers
- Find out what you can buy
Who counts as a first-time home buyer?
For most programs, you’re a first-time home buyer if you haven’t owned your primary home in the past three years. That means you can still qualify if you sold a home years ago, or if you’ve only owned investment property.
Being a first-time buyer opens up the 3% down conventional loan, CalHFA’s down payment programs and some reduced-cost mortgage insurance options. FHA, VA and USDA loans don’t require it at all.
First-time home buyer loan options compared
| Loan | Minimum down | Typical minimum credit | Mortgage insurance | Good fit for |
|---|---|---|---|---|
| Conventional (incl. HomeReady, Home Possible) | 3% | 620 | Monthly PMI, removable at 20% equity | Good credit; want to drop mortgage insurance later |
| FHA | 3.5% (10% with a 500–579 score) | 580 | 1.75% upfront plus a monthly premium (about 0.55% a year on most loans) | Lower credit scores or higher debt-to-income |
| VA | 0% | No VA minimum; lenders often 580–620 | None; a one-time funding fee unless exempt | Veterans, service members, eligible spouses |
| USDA | 0% | About 640 | 1% upfront plus 0.35% a year | Eligible rural and suburban areas, income limits apply |
| Jumbo | Usually 10–20% | About 700 | Usually none | Loans above $1,104,000 in San Diego County |
In 2026 the conforming and FHA loan limit in San Diego County is $1,104,000 for a one-unit home, so many first homes here still fit a 3–3.5% down loan.
California first-time home buyer programs
The California Housing Finance Agency (CalHFA) runs the state’s main first-time buyer programs. They’re paired with a CalHFA first mortgage and have income limits by county.
| Program | What it gives you | Key rules |
|---|---|---|
| CalHFA MyHome Assistance | A deferred-payment second loan of up to 3.5% of the price with a CalHFA FHA loan, or 3% with a CalHFA conventional loan, for down payment or closing costs | First-time buyer, owner-occupied, county income limits, homebuyer education course |
| California Dream For All | Up to 20% of the price (max $150,000) as a shared appreciation loan you repay with a share of the home’s gain | First-generation buyer, income limits, awarded by drawing. The 2026 application window closed March 16, 2026 |
Assistance isn’t always the cheapest path. Some programs carry a slightly higher rate or extra fees, so I’ll compare the program against a regular 3–3.5% down loan and show you the real monthly and total cost of each.
How much cash do you need to buy your first home in San Diego?
Plan for the down payment plus closing costs, which usually run about 2–5% of the price. Here’s a $750,000 condo as an example:
| Loan | Down payment | Plus closing costs (about 2–5%) |
|---|---|---|
| Conventional, 3% down | $22,500 | $15,000–$37,500 |
| FHA, 3.5% down | $26,250 | $15,000–$37,500 |
| VA, 0% down | $0 | $15,000–$37,500 |
Seller credits, lender credits and gift funds can cover much of the closing costs. Also budget for property tax: California reassesses at your purchase price, so plan on about 1.25% of the price a year, plus homeowners insurance and any HOA or Mello-Roos.
First-time home buyer requirements
- Credit score: about 580 for FHA, 620 for conventional. I can tell you if a few points would lower your rate.
- Steady income: usually two years of work history, with explainable gaps. Self-employed? See self-employed options.
- Debt-to-income: your total monthly debts, including the new house payment, are often allowed up to about 45–50% of your gross income.
- Down payment you can document: savings, a gift from family, or an assistance program.
- Homebuyer education: required for CalHFA programs and some 3% down loans; it’s an online course you can finish in a weekend.
How to buy your first home
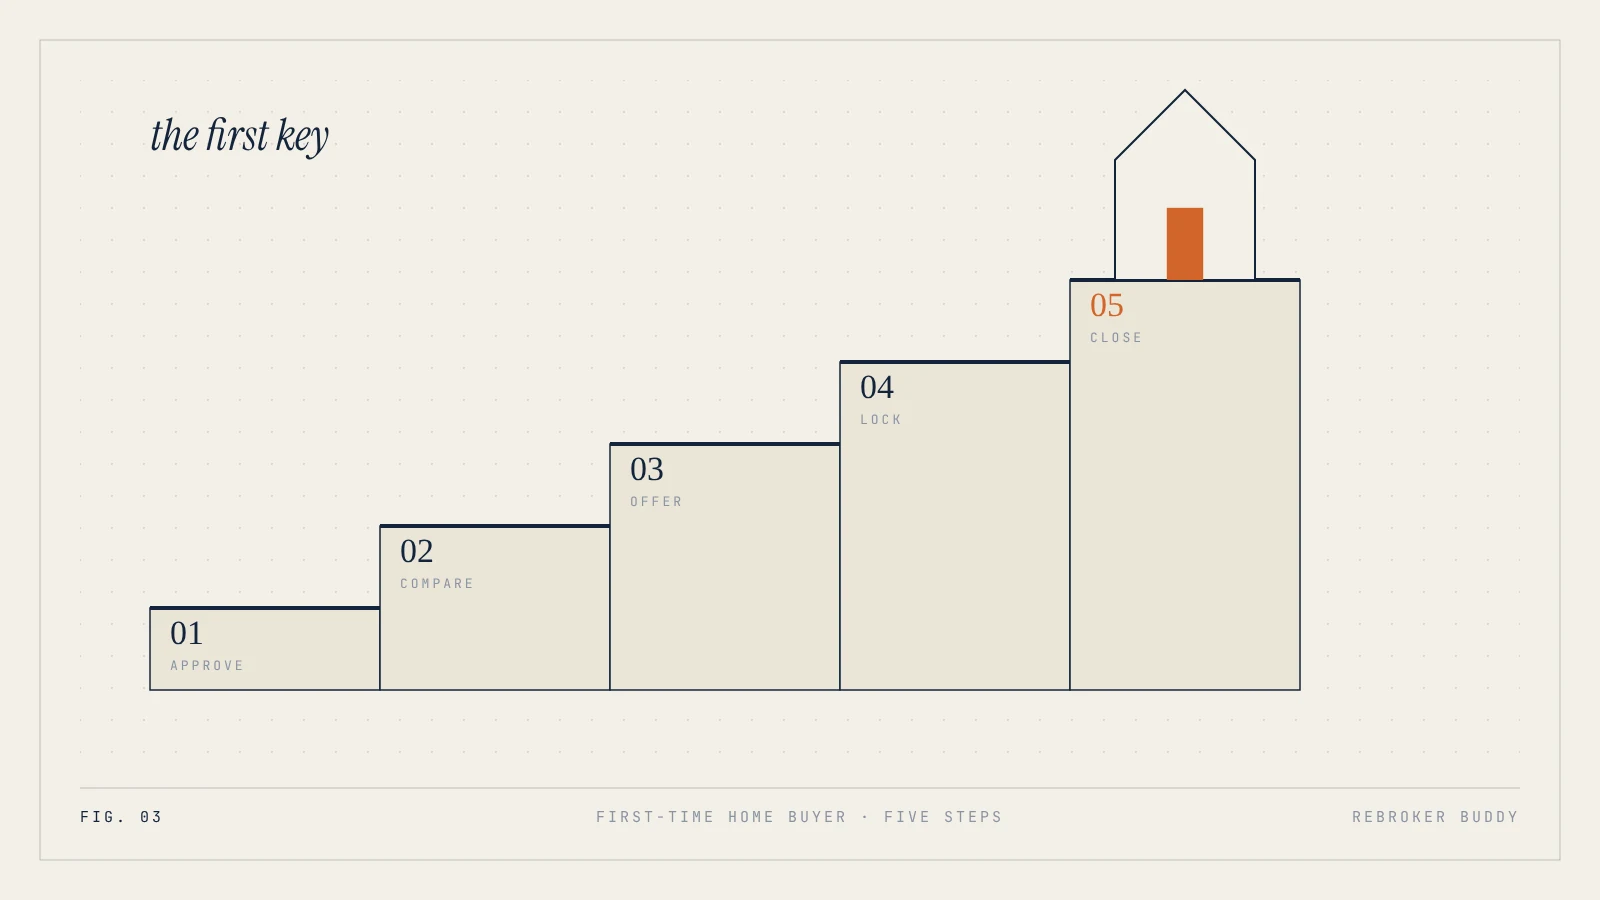
- Get pre-approved. I review your credit, income and savings and run your file through underwriting, so your letter holds up when you make an offer.
- Pick your loan. I compare conventional, FHA, VA and assistance options side by side, with the payment and cash to close for each.
- Shop and make an offer with your agent.
- Lock your rate, appraisal and underwriting. I keep you updated at each step.
- Close and get the keys, usually 21 to 30 days after your offer is accepted.
What homebuyers say
“Trevor helped us finance our home purchase. It wasn't the simplest of transactions, but he made it as smooth and painless as possible. He was great at explaining things in layman's terms and he made sure to keep us informed and updated every step of the way.”
— Nick D., home purchase, Google review
“Outstanding experience from start to finish! Trevor was professional, responsive, and made the entire process smooth and stress-free. He worked quickly, communicated clearly, and completed everything on time.”
— Paul P., FHA loan, Google review
What affects your first-home mortgage rate
I don’t post a single rate here, because yours depends on your credit, down payment, loan type and the property. See today’s mortgage rates for a starting point, then let me price your scenario across my lenders.
First-time home buyer FAQ
Who counts as a first-time home buyer?
Generally, anyone who hasn’t owned their primary home in the last three years. So you may qualify even if you owned a home before.
What is the minimum down payment for a first-time home buyer?
0% with a VA or USDA loan, 3% with a conventional loan, and 3.5% with an FHA loan. State programs like CalHFA MyHome can help cover that down payment.
What credit score do I need to buy my first home?
About 580 for FHA with 3.5% down, and 620 for most conventional loans. VA has no set minimum, but most lenders look for about 580–620. Higher scores get better rates.
Can I use gift money for my down payment?
Yes. FHA, VA and conventional loans all allow gift funds from family for the down payment and closing costs, with a signed gift letter and a record of the transfer.
Do I have to be a first-time buyer to put 3% down?
For the standard 97% conventional loan, at least one borrower must be a first-time buyer. HomeReady and Home Possible also allow 3% down without that rule, but they have income limits.
How long does it take to buy a house with a mortgage?
Most purchase loans close in about 21 to 30 days after your offer is accepted. Getting fully pre-approved first makes the rest go faster.
Which states do you help first-time buyers in?
I’m licensed for home loans in California, Arizona, Florida, Oregon, Tennessee, Texas and Washington. My office is in San Diego.
More for first-time buyers
- Home purchase loansHow buying with a mortgage works
- FHA loans3.5% down, flexible credit
- Conventional loans3% down, removable PMI
- VA loans0% down for veterans
- Get pre-approvedKnow your budget before you shop
- Bad credit home loansOptions below 620
Find out what you can buy
Tell me your savings, income and target price, and I’ll show you which first-time buyer loans and programs fit, with the cash you’d need to close.
Program terms shown are as of November 2026 and can change at any time. CalHFA program details come from calhfa.ca.gov; availability, income limits and funding are set by CalHFA. Trevor Gravink, NMLS #1707407, CA DRE #02117228. Broker Buddy LLC, CA DRE #02126109, powered by Adaptive Mortgage Solutions Inc., NMLS #2022974. Not a commitment to lend; all loans are subject to credit approval, underwriting and property eligibility.
Ready for your loan?
STEP 1
Apply Online or Call Directly
Find out how much home you can buy or discover how much you can save by refinancing.
STEP 2
Review What Options You Can Qualify For
Learn exactly how much you qualify for and what you would save by working with us.
STEP 3
Get Loan Approval in 24 Hours (weekdays)
Get mortgage loan approval to move forward with your property.


Broker Buddy LLC
Trevor Gravink
Mortgage Consultant
CEO/Owner
(619) 404-6637
NMLS: 1707407
NMLS Consumer Access Lookup Tool
CA DRE # 02117228
5371 Wilshire Dr. San Diego, CA 92116
© 2026 Broker Buddy LLC
Powered by Adaptive Mortgage Solutions
Company NMLS # 2022974
CA DRE # 02126109