DSCR Loans in San Diego, From a Local Broker Who Shops the Lenders
ReBroker Buddy is a San Diego mortgage broker, run by Trevor Gravink (NMLS #1707407), that arranges DSCR loans for rental properties across San Diego County by comparing DSCR programs from 40+ wholesale lenders. A DSCR loan in San Diego lets you buy or refinance a rental on the property's rent, with no tax returns, W-2s or pay stubs.
How does a DSCR loan work for a San Diego rental?
San Diego is a hard market to make cash flow in, so the lender you pick matters more here than almost anywhere. Every DSCR lender sets its own rules for credit, down payment, ratio and short-term rentals. I keep current matrices from each of them, so I can match your property to the one that will actually approve it.
The lender divides the property's monthly rent by its monthly payment (principal, interest, taxes, insurance and any HOA), and that number is your DSCR. If the ratio meets the lender's minimum, you qualify on the property, not your personal income.
Example: a condo in Mission Valley rents for $3,200 and the full payment is $3,000, so the DSCR is 1.07. Rent comes from the appraiser's market rent survey or an existing lease. Your job, credit and tax returns don't enter the ratio.
What are the DSCR loan requirements in San Diego?
Most of my lenders start at a 620 credit score and 20–25% down, with the best programs reaching 85% LTV on a purchase. Here's what the 10 DSCR lenders I use most allow today, taken from their October 2026 program matrices:
| Requirement | Typical across my lenders | Best available |
|---|---|---|
| Credit score | 620–700 minimum | 620 |
| Purchase LTV | 75–80% (20–25% down) | 85% (720+ credit, DSCR 1.20+, loans to $1.5M) |
| Cash-out refinance LTV | 65–75% | 80% (720+ credit, loans to $1M) |
| Minimum DSCR | 0.75–1.00 | No-ratio programs (up to about 75% LTV) |
| Max loan amount | $1.5M–$3M | $3.5M standard, $4.5M on one program |
| Short-term rentals | Allowed, 70–75% LTV, 700–720 credit | Up to 80% LTV |
| Reserves | 3–6 months of payments | 0 months on two programs |
| Interest-only / 40-year | 10-year interest-only at every lender | 40-year terms at 7 of 10 |
| Close in an LLC | Yes, with a personal guarantee | — |
Programs change often, and the exact LTV depends on your credit, ratio and loan size together. I'll price your scenario against all of them at once.
Can San Diego rents qualify at today's prices?
Often not at a 1.0 ratio with 20% down, which is why lender choice matters so much here. The fixes are a ratio-below-1.0 program, an interest-only or 40-year payment, or a larger down payment, and each lender handles them differently.
Most of my lenders accept a DSCR as low as 0.75, and a few have no-ratio programs for properties that don't cash-flow on paper. Interest-only (10 years at every lender I use) lowers the qualifying payment, which can move a 0.95 property over 1.0. Let's talk and I'll run your address through each option.
Can I use a DSCR loan for an Airbnb in San Diego?
Yes, most of my lenders allow short-term rentals, usually at 70–75% LTV with a 700–720 credit score. On a purchase, the rent comes from an AirDNA projection; on a refinance, lenders use your 12-month booking history.
Check the city license first. San Diego requires a short-term residential occupancy (STRO) license for any stay under a month. Whole-home licenses (Tier 3) are capped at 1% of the city's housing units, and as of October 23, 2026 the city showed 807 still available. Mission Beach whole-home licenses (Tier 4) are capped at 30% of the area and are closed, with a waitlist. Tier 3 and 4 hosts also need a two-night minimum and must use the license at least 90 days a year. These rules are for the City of San Diego. Other cities in the county, like Oceanside, Carlsbad, Coronado and Chula Vista, set their own short-term rental rules, so check the city the property is in before you buy. No license, no short-term rent, so I'll ask about this before we price anything.
On the lender side, most programs want AirDNA projections showing occupancy above about 60%, and some take 20% off short-term income to cover management. In my words from my DSCR rent video: "some lenders do take out 20% for being able to run the short-term rental."
Will my property taxes go up when I buy a San Diego rental?
Yes, usually by a lot. In California the property is reassessed at your purchase price when you buy, so your tax bill is based on what you paid, not on the seller's old bill, and the lender uses that new tax in your DSCR.
California's property tax rules cap the base rate at 1% of assessed value, reset assessed value to market value when a property sells, and limit increases to 2% a year after that. Local voter-approved charges come on top of the 1%, which is why I tell San Diego buyers to plan on about 1.25% of the purchase price. On a $1,000,000 duplex that's roughly $12,500 a year, or about $1,040 a month in your payment, even if the seller was paying a fraction of that after owning it for 20 years.
"You don't want to go off the current tax bill, you need to go off the new purchase price." — from my video What is a DSCR loan
What San Diego properties can I finance with a DSCR loan?
Single-family homes, townhomes, condos (including non-warrantable condos at up to 80% LTV on some programs) and 2–4 unit buildings all qualify. For 5–8 or 5–9 unit buildings, some of my lenders go to 75% LTV; see DSCR loans for 5–9 units.
That covers a downtown condo, a duplex in North Park, a fourplex in City Heights or a beach-area rental. You can close in your name or an LLC with a personal guarantee.
How much can I borrow on a San Diego DSCR loan?
Standard DSCR programs go up to $3.5 million, and one of my lenders goes to $4.5 million. DSCR loans aren't bound by conforming loan limits, so a San Diego price doesn't push you into a separate jumbo program.
For comparison, the 2026 conforming loan limit is $832,750 in most of the country and up to $1,249,125 in high-cost areas. The largest DSCR loans usually need more reserves, often 6 to 12 months of payments.
Can I cash out equity from a San Diego rental?
Yes. The best cash-out program I have reaches 80% LTV with 720+ credit, and most lenders want you to have owned the property 6 months first. If you've owned it less than that, a few lenders will use your purchase price plus improvements.
Long-time San Diego owners often have the equity to fund their next purchase this way. See DSCR cash-out refinance for the details.
Why use a San Diego broker instead of a national DSCR lender?
A direct lender can only offer its own program; I compare DSCR programs across 40+ wholesale lenders and send your file to the one that fits. In a market where the numbers are tight, that's often the difference between a "no" and a closed loan.
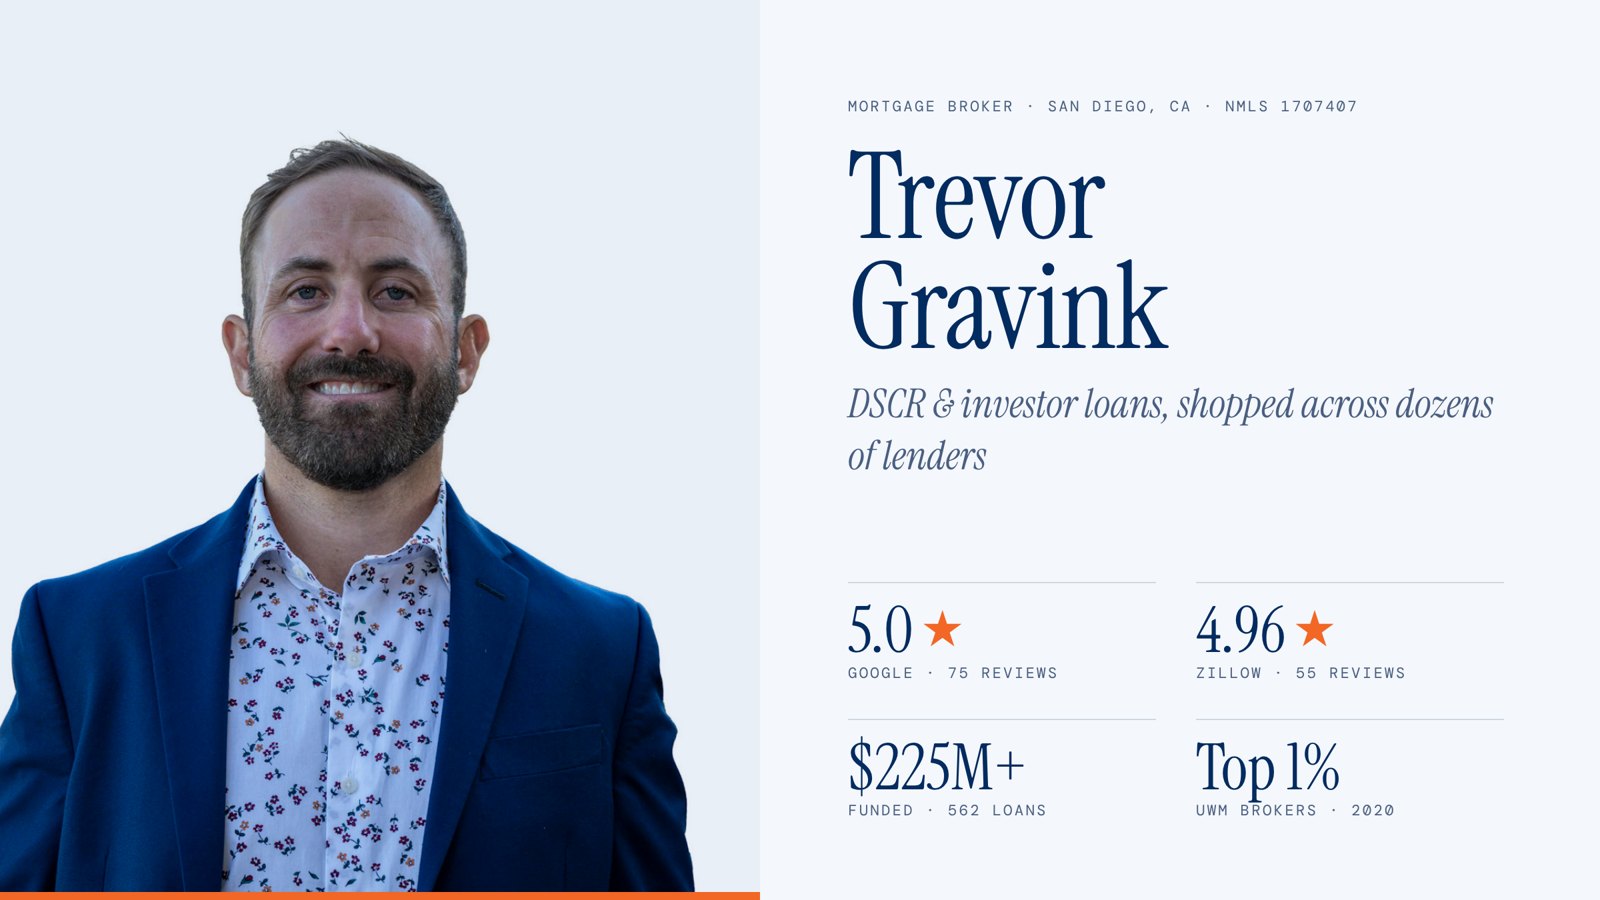
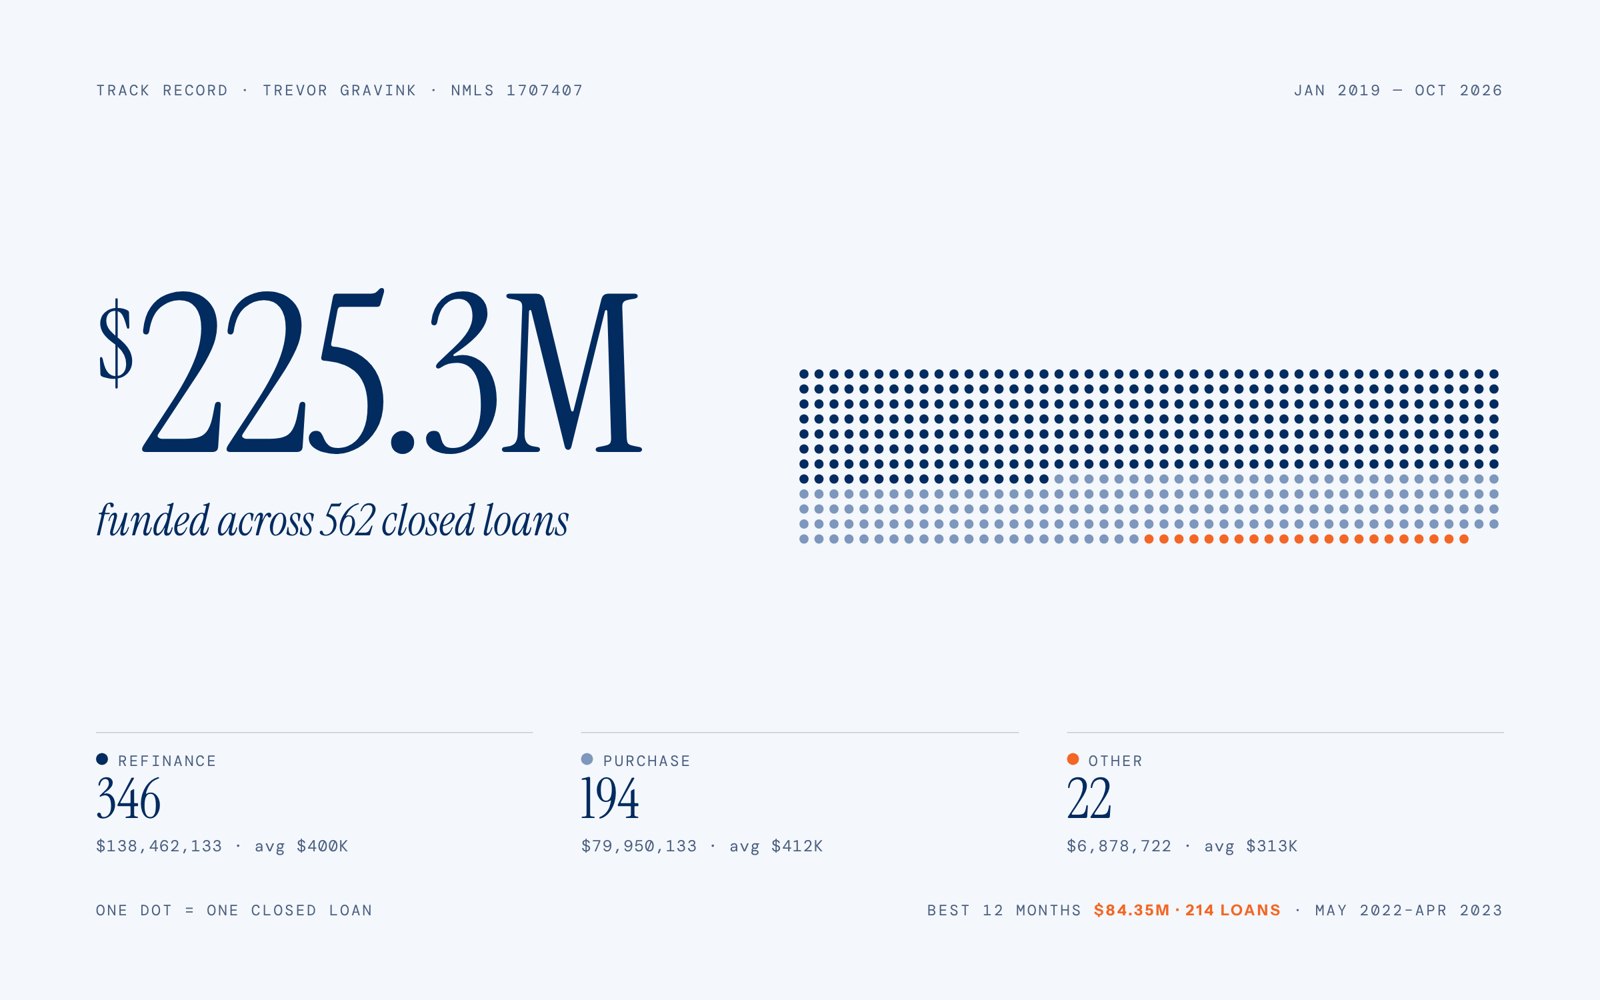
Since 2019 I've closed 562 loans totaling $225.3 million: 346 refinances, 194 purchases and 22 others. In 2020, United Wholesale Mortgage named me to its Top 1% of brokers.
What investors say
“Trevor helped get us quickly to closing on a multifamily property when a competing DSCR lender could not. We closed in under 3 weeks! Trevor did a lot of up front work and shopped around DSCR lenders to get the best rate.”
— Ryan B., Google review
“I had already gone through multiple lenders that were unable to get my file to the finish line, and Trevor was the person who finally got it done.”
— Waldy C., Google review
“Working with Trevor on my first DSCR loan was a great experience. Of all the homes I've purchased, this was by far the easiest financing process.”
— Curtis P., Google review
“I'm a full time investor with 20-ish units, and loans are usually a nightmare. Trevor turned it into a semi-smooth, walkable path.”
— Darwin C., Google review
“Trevor was responsive, helpful, and worked hard to get me the best DSCR rate.”
— Michael T., Google review
Watch: What is a DSCR Loan, with Trevor Gravink.
How do I get a DSCR loan in San Diego?
- Send the property. Address, price, expected rent, and whether it's long-term or short-term.
- I run it against every lender. You get the programs that fit, with the down payment, ratio and terms side by side.
- Apply once. No tax returns: credit, bank statements for down payment and reserves, the lease or rent estimate, and LLC documents if you're using one.
- Appraisal and rent survey. The appraiser confirms value and market rent.
- Close. In your name or your LLC.
Reviews from our clients
San Diego DSCR loan FAQ
What credit score do I need for a DSCR loan in San Diego?
620 is the lowest I can offer today, but 680–700+ opens up more programs and higher LTVs.
Can a first-time investor get a DSCR loan?
Yes, several of my lenders allow first-time investors, usually at up to 75–80% LTV. If you've never owned any home, options are fewer, but a few programs allow it.
Is there a prepayment penalty?
Usually, from 0 to 5 years, and you can often choose a shorter one in exchange for a slightly different price.
Do you post DSCR rates?
Not on this page, because your rate depends on credit, LTV, ratio and prepay choice. See today's DSCR rates for this week's starting point, or let's talk for your exact numbers.
More DSCR loan options
Let's talk about your San Diego rental
Send me the address and the rent, and I'll show you which of my lenders will do it and on what terms. No tax returns needed to get started.
Prefer to talk first? Call or text (619) 404-6637 or book a free consultation.
DSCR loans are business-purpose loans for non-owner-occupied investment properties. Ranges shown are typical of the lenders we work with as of October 2026 and can change at any time. Short-term rental and property tax information is general and not legal or tax advice. Broker Buddy LLC, NMLS #2022974. Trevor Gravink NMLS #1707407. Not a commitment to lend; all loans subject to credit approval and property eligibility.
STEP 1
Apply Online or Call Directly
Find out how much home you can buy or discover how much you can save by refinancing.
STEP 2
Review What Options You Can Qualify For
Learn exactly how much you qualify for and what you would save by working with us.
STEP 3
Get Loan Approval in 24 Hours
Get mortgage loan approval to move forward with your property.



Broker Buddy LLC
Trevor Gravink
Mortgage Consultant
CEO/Owner
(619) 404-6637
NMLS: 1707407
NMLS Consumer Access Lookup Tool
CA DRE # 02117228
5371 Wilshire Dr. San Diego, CA 92116
© 2026 Broker Buddy LLC
Powered by Adaptive Mortgage Solutions
Company NMLS # 2022974
CA DRE # 02126109
