Fixed-Rate Home Equity Loan: One Lump Sum, One Set Payment
A home equity loan (also called a HELOAN or closed-end second mortgage) gives you one lump sum from your home's equity at a fixed rate, paid back with the same payment every month. It sits behind your first mortgage, so your current rate and payment stay the same.
On this page
How a home equity loan works
- You get the full amount at closing.
- The rate is fixed for the life of the loan.
- Terms run 10, 15, 20 or 30 years. A shorter term means a higher payment but less interest overall.
- Your first mortgage doesn't change.
It can also be used at purchase as a "piggyback" second mortgage, to lower your down payment or keep your first mortgage under the conforming loan limit.
How much can you borrow?
Example: your home is worth $600,000 and you owe $300,000. At 85% combined loan-to-value, total loans can reach $510,000, so your home equity loan could be up to about $210,000.
Home equity loan requirements
| Typical range | |
|---|---|
| Credit score | 640 minimum with full documentation on a primary home; 700+ for the highest loan-to-value |
| Combined loan-to-value | Up to 90% on a primary home (700+ credit, loans up to $350,000); up to 80% on second homes and rentals |
| Loan amount | $100,000 to $1,000,000 |
| Debt-to-income | Up to about 50% |
| Terms | 10 to 30 years, fixed |
| Home value | Automated valuation plus a property inspection on 1-unit loans up to $400,000; full appraisal above that and on 2–4 units |
| Occupancy | Primary home, second home or rental |
| States | Most states, but not New York. Texas has special home equity rules, so call us first |
Investor using rental income? See the DSCR home equity loan and DSCR second mortgage.
Home equity loan vs. HELOC vs. cash-out refinance
- Home equity loan: best when you need a set amount now and want a fixed payment.
- HELOC: best when you'll draw over time or want a safety net.
- Cash-out refinance: replaces your whole first mortgage. Usually only worth it when your current rate is already near today's rates.
What affects your rate
We don't post rates. Your fixed rate depends on your credit score, combined loan-to-value, loan amount, term length, occupancy and debt-to-income. A higher score and more equity left in the home usually mean a better rate. Let's talk and we'll lay out the options side by side.
Mistakes to avoid
- Picking the longest term by default. It lowers the payment but adds interest. Compare a 15- or 20-year term too.
- Borrowing for something you'll pay for over years. If you'll spend the money slowly, a HELOC may cost less.
- Forgetting your first mortgage's balance and terms. Bring a recent statement so we size the loan correctly.
Recently funded: $150,000 home equity loan on a Scottsdale 4-plex
Darwin C., a full-time investor with about 20 units, wanted to pull cash out of a 4-unit rental in Scottsdale without refinancing the first mortgage. We closed a fixed-rate home equity loan (a second mortgage) behind his existing loan, qualified him on a profit-and-loss statement because he’s self-employed, and valued the property with an automated valuation combined with a drive-by appraisal instead of a full interior appraisal.
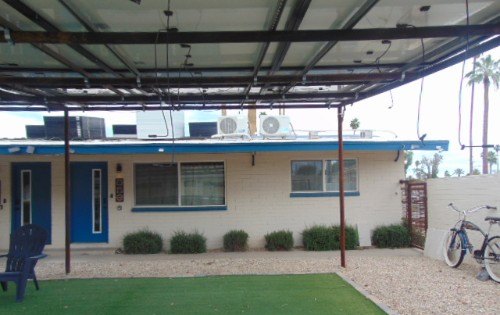
The property’s shared courtyard, from the drive-by appraisal (April 2026).
| Detail | This loan |
|---|---|
| Property | 4-unit multifamily rental (investment property), Scottsdale, AZ |
| Loan | $150,000 fixed-rate second mortgage, 30-year, fully amortizing |
| Payment | $1,275/mo principal & interest; taxes and insurance paid separately |
| Income documentation | Profit-and-loss statement (self-employed sole proprietor), no tax returns |
| Credit | 708 middle score |
| Value | $1,263,966 from an automated valuation combined with a drive-by (exterior-only) appraisal |
| First mortgage | About $501,000, kept in place |
| Combined LTV | About 52% |
| Prepayment penalty | None |
| Closing costs | $2,372 after a $2,250 lender credit |
| Timeline | Applied March 30, closed May 28, 2026 |
What made it work
- The first mortgage stayed in place. Only the new $150,000 is at today’s pricing; the existing loan’s rate and payment didn’t change.
- Low combined LTV (about 52%) left plenty of equity cushion, which is what lenders look at most on a second lien.
- Fixed rate and payment for 30 years, with no prepayment penalty.
- No full interior appraisal – the value came from an automated valuation combined with a drive-by appraisal.
- Valuation exception – the automated valuation came back at 77% confidence, below the lender’s usual 80% minimum. We got the lender to approve an exception, backed by the drive-by appraisal.
“Loan was a complete PITA, and Trevor handled the bumps and setbacks like a champ and got us over the finish line. What more can you ask for? I’m a full time investor with 20-ish units, and loans are usually a nightmare. Trevor turned it into a semi-smooth, walkable path. Thanks again! Will be back here on the next one.” — Darwin C., 5-star Google review
Real results
"Trevor did a great job helping me out with a HELOC. He made the whole process really easy to understand, he gave multiple options and outlined exactly what everything meant and helped guide me into what was the best solution for what I was looking for. This was the second time working with Trevor, and he is the only person I would go back to in the future." — Max S., 5-star Google review
Reviews from our clients
Home equity loan FAQ
What's the difference between a home equity loan and a HELOC?
A home equity loan is one lump sum at a fixed rate. A HELOC is a credit line you can draw from and reuse.
What credit score do I need?
Primary-home loans with full documentation start at 640. A 700+ score opens the highest loan-to-value options.
How long are the terms?
Usually 10 to 30 years.
Can I get a home equity loan on a rental property?
Yes. Many programs allow second homes and rentals, and DSCR versions qualify on the rent.
Is the interest tax-deductible?
Sometimes, when the money is used to buy, build or improve the home. Ask your tax advisor.
Get your home equity loan options
Tell us your home's value, what you owe and how much you need, and we'll compare terms and payments side by side. Call or text 619-404-6637.
Prefer to talk first? Call or text (619) 404-6637 or book a free consultation.
HELOCs and home equity loans are secured by your home. Rates, terms and availability vary by state, credit, property and loan amount; Texas home equity loans have different rules. Broker Buddy LLC, NMLS #2022974. Trevor Gravink NMLS #1707407. Not a commitment to lend; all loans subject to credit approval and property eligibility. Programs, guidelines and ranges shown are typical of the lenders we work with and can change at any time.
STEP 1
Apply Online or Call Directly
Find out how much home you can buy or discover how much you can save by refinancing.
STEP 2
Review What Options You Can Qualify For
Learn exactly how much you qualify for and what you would save by working with us.
STEP 3
Get Loan Approval in 24 Hours (weekdays)
Get mortgage loan approval to move forward with your property.


Broker Buddy LLC
Trevor Gravink
Mortgage Consultant
CEO/Owner
(619) 404-6637
NMLS: 1707407
NMLS Consumer Access Lookup Tool
CA DRE # 02117228
5371 Wilshire Dr. San Diego, CA 92116
© 2026 Broker Buddy LLC
Powered by Adaptive Mortgage Solutions
Company NMLS # 2022974
CA DRE # 02126109