Looking for a DSCR Loan in Florida?
We are the experts!
Qualify Based on Rental Income Only!
No Personal Income Needed to Qualify!
Interest Only Options Available!
Fund Into Corporation or LLC
No Pre-Pay Options
AirBnB's Allowed
Answer a Few Quick Questions and Let’s See if You’re Eligible
🔒 This site is secure
🔒 This site is secure
Qualify Based on bank statements only!
No W2's or Tax Returns Needed!
Interest Only Options Available!
Get up to 90% Financing
100% Gift Funds Allowed
Fixed Rate and Adjustable Rate Options
DSCR Loans in Florida: Finance Rentals on the Property's Income
A DSCR (debt service coverage ratio) loan lets Florida investors qualify using the rent a property earns instead of personal tax returns, W-2s, or pay stubs. If the rent covers the mortgage payment, taxes, insurance, and any HOA dues, the property can usually carry its own loan. Florida's rental demand spans year-round metros (Miami, Tampa, Orlando, Jacksonville) and seasonal tourist and coastal markets, and South Florida has the state's highest HUD Fair Market Rents. Investors should budget for the fact that rentals do not get the homestead exemption or the 3% Save Our Homes cap, and that insurance and hurricane risk weigh heavily on operating costs.
Broker Buddy shops DSCR programs from multiple wholesale lenders for single-family homes, 2–4 unit properties, condos and townhomes across all 67 Florida counties — purchases, rate-and-term refinances, and cash-out refinances.
Florida DSCR Loan Guidelines at a Glance
Every DSCR lender has its own guidelines, and Florida adds a few wrinkles of its own — insurance, condos and closing taxes. Most Florida rental loans fall inside these ranges, and because we compare several lenders, a rule that sinks one program often doesn't apply at another.
| Guideline | Typical range in Florida |
|---|---|
| Credit score | Many programs start around 620–660; 700+ earns the most leverage and the best pricing |
| Down payment / LTV | Usually 20–25% down (up to 80% LTV) on purchases and rate-and-term refinances; cash-out generally tops out near 75% LTV, and condos or short-term rentals may need more down |
| Minimum DSCR | 1.00 is the usual target; some programs accept 0.75–0.99, and no-ratio options exist when high insurance premiums squeeze the ratio |
| Insurance | Lenders count the actual quoted premium, including wind and any required flood policy. Get a binding quote early — insurance can be the deciding factor on coastal deals |
| Condos | Associations must complete milestone structural inspections and structural integrity reserve studies on buildings three or more stories tall. Underfunded reserves, pending special assessments or rental limits can make a project non-warrantable, which narrows the lender list |
| Closing taxes | A new mortgage carries documentary stamp tax of 35 cents per $100 of the loan and a 2-mill (0.2%) nonrecurring intangible tax, on top of the deed stamps on the purchase |
| Loan size | Minimums commonly start around $75,000–$100,000, with jumbo DSCR programs for Miami, Naples and Gulf Coast waterfront homes |
| Who can borrow | Individuals or an LLC; out-of-state entities usually register with the Florida Division of Corporations before closing |
| Time to close | About 3–5 weeks once the appraisal is ordered; condo questionnaires and insurance binders can add time |
Guidelines change often and vary by lender, credit and property. Check the ratio with our DSCR calculator, or see how 30-year, 40-year, interest-only and ARM terms change the payment and DSCR.
Why Investors Are Buying Rentals in Florida
- Tourism is a major demand driver: Walt Disney World, Universal Orlando and SeaWorld anchor the Orlando market, and Florida welcomed roughly 143 million visitors in 2024.
- PortMiami, which bills itself as the Cruise Capital of the World, reported a record 8.56 million cruise passengers in its latest fiscal year and cites more than 340,000 jobs tied to the port.
- Publix Super Markets, founded in Winter Haven in 1930, employs more than 260,000 people across 1,446 stores in eight Southeast states.
- NASA's Kennedy Space Center on the Space Coast has a workforce of more than 10,000 and works with about 100 private-sector partners as a multi-user spaceport.
- The 12-university State University System serves more than 430,000 students, including the University of Central Florida in Orlando (70,674 students in fall 2025, the largest in the state), and MacDill Air Force Base in Tampa hosts U.S. Central Command and U.S. Special Operations Command.
Florida Rental Markets Worth a Closer Look
Florida is several rental markets in one state, each with its own price points, insurance costs and tenant base. Here's how investors usually break it down — underwrite the exact address before you offer.
Miami-Dade, Broward and Palm Beach counties have deep rental demand from finance, trade and tourism jobs. Condos dominate the inventory, so association reserves and insurance costs matter as much as the rent.
Theme parks, the University of Central Florida, healthcare and a large convention business keep long-term demand strong, while Kissimmee and Davenport near the parks are vacation-rental hubs with many resort communities zoned for short stays.
Tampa, St. Petersburg and Clearwater benefit from MacDill Air Force Base, the University of South Florida, the port and a growing finance sector. Pasco and Hillsborough suburbs offer newer single-family homes.
Naval Air Station Jacksonville, Naval Station Mayport, logistics and healthcare support one of the state's more affordable large rental markets, with St. Augustine adding vacation demand.
Fort Myers, Cape Coral and Naples attract retirees, seasonal renters and healthcare workers. Flood zone and elevation drive insurance costs here, so check FEMA maps before you underwrite.
Pensacola and the Emerald Coast pair Naval Air Station Pensacola and Eglin Air Force Base with beach tourism in Destin and 30A, while Gainesville (University of Florida) and Tallahassee (Florida State) offer student rentals.
Want a quick read on what a Florida property should rent for before you write an offer? Try our free DSCR rent estimate tool.
Florida Rent Benchmarks
Lenders qualify DSCR loans using the lower of the current lease or an appraiser's market-rent estimate, so it helps to know where local rents sit before you make an offer. HUD's Fair Market Rents are a useful, neutral starting point:
| Area | 2-bedroom | 3-bedroom | 4-bedroom |
|---|---|---|---|
| Miami-Miami Beach-Kendall HMFA | $2,564 | $3,277 | $3,749 |
| Fort Lauderdale HMFA | $2,321 | $3,172 | $3,662 |
| West Palm Beach-Boca Raton HMFA | $2,349 | $3,052 | $3,523 |
| North Port-Bradenton-Sarasota MSA | $2,188 | $2,775 | $3,309 |
| Naples-Marco Island MSA | $2,036 | $2,584 | $2,815 |
| Tampa-St. Petersburg-Clearwater MSA | $1,917 | $2,448 | $2,977 |
| Orlando-Kissimmee-Sanford MSA | $1,959 | $2,445 | $2,856 |
| Palm Bay-Melbourne-Titusville MSA | $1,779 | $2,382 | $2,707 |
| Cape Coral-Fort Myers MSA | $1,835 | $2,373 | $2,615 |
| Jacksonville HMFA | $1,694 | $2,077 | $2,594 |
Source: HUD Fair Market Rents, FY2027 schedule (effective October 1, 2026). Fair Market Rents are a government benchmark, not an appraisal; actual market rent for a specific property may be higher or lower.
How Much Can a Miami-Dade County Rental Support?
A quick way to size a deal is to work backward from the rent. Using the HUD 3-bedroom benchmark for the Miami-Dade County area and some simple assumptions, here's roughly what purchase price that rent can carry with 20% down:
| Monthly rent (HUD 3-bedroom benchmark) | $3,277 |
| Purchase price the rent covers at a 1.00 DSCR | about $489,000 |
| Purchase price for a 1.20 DSCR (better pricing) | about $407,000 |
| Median value of owner-occupied homes, Miami-Dade County | $463,000 |
Benchmark rents can support a typical home in the area, which is why many investors here qualify at or above a 1.00 DSCR. Assumptions: 30-year fixed at a 7.25% example rate, with taxes and insurance estimated at 1.5% of the price per year. The median value is from U.S. Census QuickFacts. These are illustrations only — request a quote for numbers on your property.
Plug your own Florida price, rent, HOA dues and insurance quote into the DSCR calculator, or see whether an interest-only or 40-year term helps a tight deal reach 1.00.
Florida Prepayment Penalty Rules for DSCR Loans
Florida is one of the states where lenders may include a standard prepayment penalty on investment-property (business-purpose) loans. Choosing a prepayment penalty usually lowers your rate; choosing no penalty gives you the freedom to sell or refinance at any time. We'll price both ways so you can compare.
| Prepay option | How it works | Best for |
|---|---|---|
| Flat 5% (1–5 years) | 5% of the amount prepaid during the penalty term, e.g. 5/5/5 for a 3-year term. | Long-term buy-and-hold; often the best rate |
| Step-down (5-4-3-2-1 or 3-2-1) | The penalty drops each year, e.g. 5% in year 1, 4% in year 2, down to 0% after year 5. Offered by many lenders. | A balance of rate and flexibility |
| Six months' interest | Offered by some lenders: the penalty is capped at six months of interest on 80% of the original balance. | Investors who want a smaller, predictable penalty |
| No prepayment penalty | Sell or refinance any time with no penalty, at a higher rate or price. | Flips-to-rentals, BRRRR, short holds |
Florida-Specific Costs and Rules for Investors
Property taxes on rentals
Florida's homestead exemption (up to $50,000, with only the first $25,000 applying to school taxes) and the Save Our Homes cap (assessment increases limited to the lesser of 3% or CPI) apply only to an owner's permanent residence, and renting the unit disqualifies it. Non-homestead property such as rentals and second homes gets an automatic 10% annual cap on assessed value increases for non-school levies; the cap does not apply to school taxes. A sale or change of ownership or control resets the property to full market value the following year. Amendment 3 on the November 3, 2026 ballot (60% approval needed) would lower the non-homestead cap to 5% for non-school taxes starting January 1, 2027. Source: Florida Department of Revenue: Property Tax Information for Homeowners (PT-113).
Insurance, hurricane and flood risk
Florida insurers must offer hurricane deductible options of $500, 2%, 5% or 10% of the dwelling limit, applied once per calendar year to all hurricane losses with the same insurer group, and standard hurricane coverage does not include flooding. Citizens Property Insurance, the state-created insurer of last resort, now requires residential policyholders to carry flood insurance, phased in by replacement cost so that all personal residential policies must have it by January 1, 2027. A property is generally ineligible for Citizens if a private insurer offers comparable coverage within 20% of the Citizens premium. See Florida Department of Financial Services: Florida's Hurricane Deductible.
Short-term rentals and lodging tax
Florida taxes transient rentals of six months or less, including single-family homes, condos and vacation houses, at the 6% state sales tax plus any county discretionary sales surtax. Counties may add a local tourist development tax, and most counties self-administer it, so it is reported and paid to the county rather than the state. Owners and anyone who collects rent on their behalf must register with the Department of Revenue, with each rental location registered separately. Leases longer than six months are exempt. Details: Florida Department of Revenue: Sales and Use Tax on Rental of Living or Sleeping Accommodations (GT-800034).
Landlord-tenant law
Long-term rentals are governed by the Florida Residential Landlord and Tenant Act (Part II of Chapter 83, Florida Statutes). Florida law does not cap the amount of a security deposit. After the tenant moves out, the landlord has 15 days to return the deposit if no claim is made, or 30 days to send written notice by certified mail of an intent to claim part of it (s. 83.49, F.S.). Read more: Florida Statutes s. 83.49: Deposit money or advance rent.
Eviction notices and ending a tenancy
For unpaid rent, a Florida landlord serves a written 3-day notice to pay or leave, and the 3 days don't count Saturdays, Sundays or court-observed holidays. For a lease violation the tenant can fix, the notice gives 7 days to cure. A month-to-month tenancy is ended with at least 30 days' written notice before the end of a monthly period (60 days for year-to-year). Sources: Fla. Stat. § 83.56 and § 83.57.
No local rent control
The 2023 Live Local Act removed the narrow emergency path that once let Florida local governments adopt rent control, and state law now preempts local regulation of residential tenancies covered by the landlord-tenant act. Rent increases are governed by your lease. Sources: SB 102 (2023) and Fla. Stat. § 83.425.
No state income tax, but closing taxes add up
Florida has no personal income tax, so net rental profits face only federal tax. The trade-off shows up at closing: a new mortgage pays documentary stamp tax of 35 cents per $100 plus a 2-mill intangible tax, so a $300,000 DSCR loan carries roughly $1,650 in those two taxes alone. Sources: Florida Department of Revenue and Fla. Stat. § 199.133.
Buying in an LLC
Florida LLCs file Articles of Organization with the Department of State's Division of Corporations (Sunbiz) for $125: a $100 filing fee plus a $25 registered agent designation fee. Start here: Florida Sunbiz: start an LLC. Talk to your attorney or CPA about the right structure for your situation.
Florida County Property Appraiser Offices
In Florida, each county's Property Appraiser sets assessed values. Use these official sites to look up a property's value, exemptions and parcel details before you make an offer.
| County | Major cities | Office |
|---|---|---|
| Miami-Dade County | Miami, Hialeah, Miami Beach, Homestead | Property Appraiser of Miami-Dade County |
| Broward County | Fort Lauderdale, Hollywood, Pembroke Pines, Coral Springs | Broward County Property Appraiser |
| Palm Beach County | West Palm Beach, Boca Raton, Boynton Beach, Delray Beach | Palm Beach County Property Appraiser's Office |
| Hillsborough County | Tampa, Brandon, Plant City | Hillsborough County Property Appraiser |
| Orange County | Orlando, Winter Park, Apopka, Ocoee | Orange County Property Appraiser |
| Duval County | Jacksonville, Jacksonville Beach, Atlantic Beach | Duval County Property Appraiser |
| Pinellas County | St. Petersburg, Clearwater, Largo | Pinellas County Property Appraiser |
| Lee County | Cape Coral, Fort Myers, Bonita Springs | Lee County Property Appraiser |
| Polk County | Lakeland, Winter Haven, Haines City | Polk County Property Appraiser |
| Brevard County | Palm Bay, Melbourne, Titusville, Cocoa | Brevard County Property Appraiser's Office |
| Pasco County | New Port Richey, Wesley Chapel, Zephyrhills, Dade City | Pasco County Property Appraiser |
| Volusia County | Daytona Beach, Deltona, DeLand, Ormond Beach | Volusia County Property Appraiser's Office |
| Seminole County | Sanford, Altamonte Springs, Oviedo, Lake Mary | Seminole County Property Appraiser's Office |
| Sarasota County | Sarasota, North Port, Venice | Sarasota County Property Appraiser |
| Manatee County | Bradenton, Palmetto, Lakewood Ranch | Manatee County Property Appraiser |
| Collier County | Naples, Marco Island, Immokalee | Collier County Property Appraiser |
Other counties: The Florida Department of Revenue's Find a County Official page links to each county's property appraiser, tax collector and value adjustment board. View the directory.
More Free Resources for Florida Investors
- HUD Fair Market Rents — rent benchmarks by county and ZIP code
- U.S. Census QuickFacts: Florida — population, income, and housing data
- FEMA Flood Map Service Center — look up the flood zone for any address
- Florida Department of Revenue: Sales and Use Tax on Rental of Living or Sleeping Accommodations (GT-800034) — short-term rental tax rules
- Florida Sunbiz: start an LLC — form or look up an entity
Florida DSCR Loan Options & Free Tools
Florida investors use DSCR financing for more than a basic 30-year purchase. Explore the option that fits your plan:
Check whether a Jacksonville single-family or Tampa duplex covers its payment, real insurance quote included.
Estimate market rent for an Orlando or Fort Myers rental the way a DSCR appraiser will.
See how much cash you could pull from a Miami condo or Cape Coral home with a cash-out refinance.
Compare 30-year fixed, 40-year, interest-only and ARM options when Florida insurance squeezes the ratio.
Tap equity in a Florida rental without giving up a low-rate first mortgage.
Finance Kissimmee, Destin, 30A and Gulf Coast vacation rentals using projected nightly income.
Florida DSCR Loan FAQs
How much do I need to put down on a Florida DSCR loan?
Most DSCR programs require 20-25% down on a purchase. Select programs allow less with strong credit and a higher DSCR. Short-term rentals and properties with a DSCR under 1.0 usually need more down.
Do Florida DSCR loans have prepayment penalties?
They can. Florida permits standard prepayment penalties on investment loans, such as a flat 5% for 1-5 years or a 5-4-3-2-1 step-down, depending on the lender. You can also choose a loan with no prepayment penalty, typically at a slightly higher rate.
Can I use Airbnb income to qualify?
Yes, on eligible programs. Lenders use your booking history or a short-term rental market analysis for the property. Check local short-term rental licensing first.
Can I close in my LLC?
Yes. DSCR loans can close in the name of an LLC or corporation, with the owners signing a personal guarantee.
Do Florida rental properties get the 3% Save Our Homes cap?
No. Save Our Homes applies only to homestead property (an owner's permanent residence). Rentals and other non-homestead property get a separate 10% annual cap on assessed value increases for non-school taxes, which resets to market value after a sale or change of ownership. Amendment 3 on the November 3, 2026 ballot would lower that cap to 5% starting in 2027 if 60% of voters approve it.
If my Florida rental is insured by Citizens, do I need flood insurance?
Yes, under a phased requirement. Citizens requires residential policyholders to carry flood insurance (dwelling coverage is enough), phased in by replacement cost: $600,000 and up by 2024, $500,000 by 2025, $400,000 by 2026, and all other personal residential policies by January 1, 2027. Policies that exclude wind coverage and condo unit-owner policies are exempt.
What credit score do I need for a Florida DSCR loan?
Many DSCR programs start around a 620 to 660 credit score. Scores of 700 and above usually qualify for the highest loan-to-value and the best pricing, while lower scores generally need a larger down payment.
Can I get a DSCR loan on a Florida condo?
Often, yes, but the lender reviews the building as well as the unit. Underfunded reserves, unfinished milestone inspections, large special assessments or rental restrictions can make a project non-warrantable, so we look for a lender whose condo rules fit.
How does Florida insurance affect my DSCR?
The lender adds the actual quoted homeowners, wind and any required flood premium into the monthly payment. A high premium can drop a ratio below 1.00, so get a quote before you go under contract.
How much notice does a Florida landlord give for unpaid rent?
Florida uses a 3-day notice to pay rent or vacate, and weekends and court-observed holidays don't count toward the 3 days. If the tenant doesn't pay, the landlord can file an eviction in county court.
Get a Florida DSCR Rate Quote
Tell us about the property and we'll shop multiple DSCR lenders so you can compare options. No credit check to see your options.
Check My EligibilityLooking for another state? See all DSCR loan states.
DSCR Loans Explained
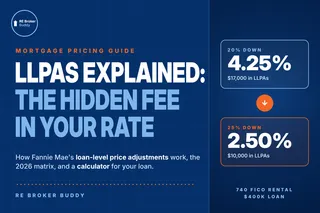
LLPA Explained: Fannie Mae's Loan-Level Price Adjustment Matrix (2026)
What a loan-level price adjustment (LLPA) is, how it works, the 2026 Fannie Mae LLPA matrix, investment property LLPAs, real-dollar examples and a calculator. ...more
DSCR loans ,Mortgage Market Updates
October 28, 2026
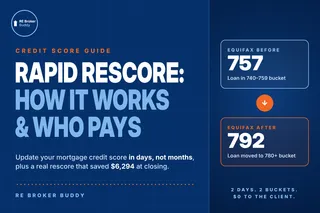
Rapid Rescore: How It Works, How Long It Takes and Who Pays
What a rapid rescore is, how it works, how long it takes, what it costs and who pays, what it can't fix, and a real rescore that saved $6,294 at closing. ...more
DSCR loans
October 28, 2026
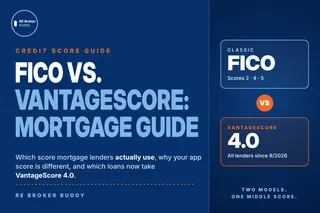
FICO vs. VantageScore for Mortgages: Which Credit Score Do Lenders Use?
Which credit score mortgage lenders use, how classic FICO and VantageScore 4.0 differ, why Credit Karma doesn't match your mortgage score, and which loans now accept VantageScore 4.0. ...more
DSCR loans ,Mortgage Market Updates
October 28, 2026
Where We Offer DSCR Loans
*Must Close in LLC
STEP 1
Apply Online or Call Directly
Find out how much home you can buy or discover how much you can save by refinancing.
STEP 2
Review What Options You Can Qualify For
Learn exactly how much you qualify for and what you would save by working with us.
STEP 3
Get Loan Approval in 24 Hours
Get mortgage loan approval to move forward with your property.



Broker Buddy LLC
Trevor Gravink
Mortgage Consultant
CEO/Owner
(619) 404-6637
NMLS: 1707407
NMLS Consumer Access Lookup Tool
CA DRE # 02117228
5371 Wilshire Dr. San Diego, CA 92116
© 2026 Broker Buddy LLC
Powered by Adaptive Mortgage Solutions
Company NMLS # 2022974
CA DRE # 02126109
