Looking for a DSCR Loan in Louisiana?
We are the experts!
Qualify Based on Rental Income Only!
No Personal Income Needed to Qualify!
Interest Only Options Available!
Fund Into Corporation or LLC
No Pre-Pay Options
AirBnB's Allowed
Answer a Few Quick Questions and Let’s See if You’re Eligible
🔒 This site is secure
🔒 This site is secure
Qualify Based on bank statements only!
No W2's or Tax Returns Needed!
Interest Only Options Available!
Get up to 90% Financing
100% Gift Funds Allowed
Fixed Rate and Adjustable Rate Options
DSCR Loans in Louisiana: Finance Rentals on the Property's Income
A DSCR (debt service coverage ratio) loan lets Louisiana investors qualify using the rent a property earns instead of personal tax returns, W-2s, or pay stubs. If the rent covers the mortgage payment, taxes, insurance, and any HOA dues, the property can usually carry its own loan. Louisiana's rental markets are spread across several mid-sized metros (New Orleans, Baton Rouge, Shreveport-Bossier, Lafayette and Lake Charles), each with its own driver: tourism, state government and LSU, the military, or energy. Investors need to plan for two Louisiana-specific costs: the homestead exemption does not cover rentals, and hurricane and flood insurance is expensive.
Broker Buddy shops DSCR programs from multiple wholesale lenders for single-family homes, 2–4 unit properties, condos and townhomes across all 64 Louisiana parishes — purchases, rate-and-term refinances, and cash-out refinances.
Louisiana DSCR Loan Guidelines at a Glance
Each DSCR lender has its own rulebook, but most Louisiana rental loans fit within these ranges. In Louisiana the insurance quote often decides the deal, so we check flood zone and wind coverage early while comparing several programs.
| Guideline | Typical range in Louisiana |
|---|---|
| Credit score | Many programs start around 620–660; 700+ unlocks the highest leverage and best pricing |
| Down payment / LTV | Commonly 20–25% down (up to 80% LTV) on purchases and rate-and-term refinances; cash-out typically caps near 75% LTV |
| Minimum DSCR | 1.00 is the usual goal; some programs accept 0.75–0.99, which can help when storm insurance inflates the payment |
| Insurance in the ratio | Lenders count hazard, named-storm and any required flood premium in PITIA. Flood insurance is required in FEMA high-risk zones, and an elevation certificate can make a big difference in the flood quote. |
| Reserves | Often 3–6 months of PITIA after closing; larger loans and lower scores can require more |
| Loan size | Minimums commonly start around $75,000–$100,000; jumbo DSCR programs reach into the millions for Uptown and Garden District homes |
| Property types | Single-family, 2–4 units (including New Orleans doubles), condos, townhomes and short-term rentals; select programs cover 5–10 units and mixed-use |
| Condos | The building must pass the lender's project review, and its master insurance policy and reserves get extra scrutiny in coastal parishes |
| Who can borrow | Individuals or an LLC formed with the Louisiana Secretary of State; first-time investors are eligible on many programs |
| Time to close | About 3–5 weeks after appraisal order; Louisiana closings are handled before a notary, often a real estate attorney |
Guidelines change and vary by lender, credit and property. Test a deal with the DSCR calculator or compare 30-year, 40-year, interest-only and ARM terms to see how each moves your ratio.
Why Investors Are Buying Rentals in Louisiana
- Energy and the process industries anchor the economy: Louisiana Economic Development counts nearly 500 process-industry facilities that turn raw materials into manufacturing inputs, alongside an established oil and gas sector.
- The Port of New Orleans runs cargo terminals, a cruise terminal and the New Orleans Public Belt Railroad, and it holds a federal permit for the Louisiana International Terminal, a new container port under development in St. Bernard Parish.
- Ochsner Health, based in New Orleans, calls itself the leading nonprofit health care provider in the Gulf South and the largest academic medical center in Louisiana.
- LSU in Baton Rouge, the state's flagship university, enrolls more than 41,000 students.
- Barksdale Air Force Base in the Shreveport-Bossier City area is home to the 2nd Bomb Wing and its three B-52H squadrons, and New Orleans' festival and food scene keeps short-term rental demand steady.
Louisiana Rental Markets Worth a Closer Look
Louisiana's rental markets range from historic New Orleans doubles to suburban Baton Rouge and energy-town single-families. Use these as a starting point, and get a flood zone and insurance read on every address.
Tulane, Loyola, the medical district and year-round tourism keep renters coming. With whole-home short-term rentals tightly limited in residential areas, most investors here underwrite long-term leases on doubles and shotgun homes in neighborhoods like Mid-City, Gentilly and Algiers.
Metairie and Kenner (home to the main airport) offer suburban rentals near New Orleans jobs. Across the lake, Mandeville, Covington, Slidell and Hammond, near Southeastern Louisiana University, attract families who want newer homes.
LSU, state government and the petrochemical plants along the Mississippi River give the capital a diverse tenant base. Rentals near campus and in suburbs like Prairieville and Denham Springs stay in demand.
The University of Louisiana at Lafayette, regional hospitals and energy-services companies drive demand, and Cajun food and festival culture attract visitors. Prices are moderate compared with the New Orleans area.
Barksdale Air Force Base, LSU Health Shreveport and the riverboat casinos support rentals in the northwest. Lower purchase prices here can make it easier for rent to cover the payment.
Large LNG export projects, casino resorts and McNeese State University fuel demand from construction crews and plant workers. Furnished mid-term rentals can work for project crews, but storm-rated construction and insurance costs matter here.
Want a fast read on what a property should rent for? Use our free DSCR rent estimate tool before you make an offer.
Louisiana Rent Benchmarks
Lenders qualify DSCR loans using the lower of the current lease or an appraiser's market-rent estimate, so it helps to know where local rents sit before you make an offer. HUD's Fair Market Rents are a useful, neutral starting point:
| Area | 2-bedroom | 3-bedroom | 4-bedroom |
|---|---|---|---|
| New Orleans-Metairie | $1,480 | $1,900 | $2,233 |
| Slidell-Mandeville-Covington (St. Tammany) | $1,354 | $1,745 | $1,997 |
| Lake Charles | $1,231 | $1,467 | $1,713 |
| Baton Rouge | $1,149 | $1,456 | $1,842 |
| Hammond | $1,097 | $1,384 | $1,442 |
| Shreveport-Bossier City | $1,045 | $1,380 | $1,450 |
| Lafayette | $1,092 | $1,375 | $1,607 |
| Alexandria | $995 | $1,341 | $1,468 |
| Houma-Bayou Cane-Thibodaux | $1,098 | $1,335 | $1,443 |
| Monroe | $1,017 | $1,314 | $1,337 |
Source: HUD Fair Market Rents, FY2027 schedule (effective October 1, 2026). Fair Market Rents are a government benchmark, not an appraisal; actual market rent for a specific property may be higher or lower.
How Much Can a New Orleans Rental Support?
A quick way to size a deal is to work backward from the rent. Using the HUD 3-bedroom benchmark for the New Orleans area and some simple assumptions, here's roughly what purchase price that rent can carry with 20% down:
| Monthly rent (HUD 3-bedroom benchmark) | $1,900 |
| Purchase price the rent covers at a 1.00 DSCR | about $283,000 |
| Purchase price for a 1.20 DSCR (better pricing) | about $236,000 |
| Median value of owner-occupied homes, New Orleans | $315,700 |
Typical homes in the area cost more than a benchmark rent alone supports, so investors often put more down, choose an interest-only option, or target properties with above-benchmark rents or multiple units. Assumptions: 30-year fixed at a 7.25% example rate, with taxes and insurance estimated at 1.5% of the price per year. The median value is from U.S. Census QuickFacts. These are illustrations only — request a quote for numbers on your property.
Plug in your own New Orleans price, rent and insurance quote with the DSCR calculator, or see whether an interest-only or 40-year term helps a deal with high storm premiums reach 1.00.
Louisiana Prepayment Penalty Rules for DSCR Loans
Louisiana allows prepayment penalties on investment-property loans. For terms longer than one year, many lenders require a declining (step-down) structure rather than a flat percentage. Choosing a prepay usually lowers your rate; choosing no penalty gives you the freedom to sell or refinance at any time. We'll price both ways so you can compare.
| Prepay option | How it works | Best for |
|---|---|---|
| Step-down (5-4-3-2-1 or 3-2-1) | The penalty drops each year, e.g. 3% in year 1, 2% in year 2, 1% in year 3, then none. | Buy-and-hold investors who want a lower rate |
| 1-year prepay | A penalty applies only to a payoff in the first year. | Investors who may sell or refinance soon |
| No prepayment penalty | Sell or refinance any time with no penalty, at a higher rate or price. | Flips-to-rentals, BRRRR, short holds |
Louisiana-Specific Costs and Rules for Investors
Property taxes on rentals
Each parish assessor values property. Residential property is assessed at 10% of fair market value and commercial property at 15%. The homestead exemption takes $7,500 of assessed value (about $75,000 of market value) off the bill, but only for an owner-occupied primary residence, so rentals pay tax on their full assessed value. Property owned by a business entity such as an LLC, or used for business, does not qualify for the exemption either. Source: Louisiana House Fiscal Division - Louisiana Property Tax Basics.
Hurricane, wind and flood insurance
Louisiana insurers increasingly apply a separate hurricane or named-storm deductible, figured as a percentage of the insured value, and some coastal policies exclude wind and hail entirely. Standard policies do not cover flood, so investors need a separate NFIP or private flood policy, which lenders require in high-risk zones. Louisiana Citizens Property Insurance Corporation is the insurer of last resort for owners who cannot get coverage in the regular market. See Louisiana Department of Insurance - Homeowners Insurance.
Short-term rentals and lodging tax
State sales tax (5% since January 1, 2025) applies to room rentals, and parish and city occupancy taxes are added on top. Act 82 of 2025 made accommodations intermediaries such as Airbnb and Vrbo marketplace facilitators, so they must collect and remit the tax as of July 1, 2025. New Orleans requires a permit for any rental under 30 days. Its non-commercial residential STR permit allows only one per square, awarded by lottery, and requires the operator to live on site and the owner to hold no other STR permit. Details: Louisiana Department of Revenue - Room Rentals Using Accommodations Intermediaries (RIB 25-026).
Landlord-tenant law
Long-term rentals are governed by the Louisiana Civil Code, Title IX (Lease), and La. R.S. 9:3251 et seq. (Residential leases; security deposits). Louisiana law does not cap the security deposit amount. The landlord must return the deposit, with an itemized statement of any deductions, within one month after the lease ends. Read more: Louisiana State Legislature - Louisiana Laws search.
Notice to vacate before eviction
When a lease ends or is terminated for nonpayment, a Louisiana landlord must deliver a written notice giving the tenant at least five days to vacate before filing for eviction. Many Louisiana leases include a written waiver of this notice, which the Code of Civil Procedure allows, so the lease wording matters. Have a Louisiana attorney review your lease and notices. Source: La. C.C.P. art. 4701.
State income tax on rental profits
Louisiana replaced its graduated brackets with a flat 3% individual income tax for tax years beginning January 1, 2025, and it applies to net rental income on your state return. Ask your CPA how depreciation and LLC pass-through rules affect your actual tax. Source: Louisiana Department of Revenue.
Buying in an LLC
Louisiana LLCs are formed by filing Articles of Organization with the Louisiana Secretary of State, online through geauxBIZ. Start here: Louisiana geauxBIZ: form a business. Talk to your attorney or CPA about the right structure for your situation.
Louisiana Parish Assessor Offices
Use these official parish assessor offices to look up a property's assessed value, current tax bill and parcel details before you make an offer.
| Parish | Major cities | Office |
|---|---|---|
| Orleans Parish | New Orleans | Orleans Parish Assessor |
| Jefferson Parish | Metairie, Kenner, Gretna | Jefferson Parish Assessor |
| East Baton Rouge Parish | Baton Rouge, Central, Zachary | East Baton Rouge Parish Assessor |
| Caddo Parish | Shreveport | Caddo Parish Assessor |
| Lafayette Parish | Lafayette, Youngsville, Broussard | Lafayette Parish Assessor |
| St. Tammany Parish | Slidell, Mandeville, Covington | St. Tammany Parish Assessor |
| Calcasieu Parish | Lake Charles, Sulphur | Calcasieu Parish Assessor |
| Bossier Parish | Bossier City, Benton | Bossier Parish Assessor |
| Livingston Parish | Denham Springs, Walker | Livingston Parish Assessor |
| Tangipahoa Parish | Hammond, Ponchatoula | Tangipahoa Parish Assessor |
| Rapides Parish | Alexandria, Pineville | Rapides Parish Assessor |
| Ascension Parish | Gonzales, Prairieville, Donaldsonville | Ascension Parish Assessor |
Other parishes: The Louisiana Tax Commission oversees all 64 parish assessors, receives their annual tax rolls and hears assessment appeals. Its website lists each parish assessor's contact information. View the directory.
More Free Resources for Louisiana Investors
- HUD Fair Market Rents — rent benchmarks by county and ZIP code
- U.S. Census QuickFacts: Louisiana — population, income, and housing data
- FEMA Flood Map Service Center — look up the flood zone for any address
- Louisiana Department of Revenue - Room Rentals Using Accommodations Intermediaries (RIB 25-026) — short-term rental tax rules
- Louisiana geauxBIZ: form a business — form or look up an entity
Louisiana DSCR Loan Options & Free Tools
Louisiana investors use DSCR loans for long-term rentals, post-renovation refinances and permitted vacation rentals. Explore the option that fits your plan:
See whether a New Orleans double or a Baton Rouge single-family covers its payment, including flood and wind insurance.
Estimate market rent in Lafayette, Shreveport or the Northshore the way a DSCR appraiser will.
Find out how much cash you could pull from a renovated New Orleans or Metairie rental.
Compare 30-year fixed, 40-year, interest-only and ARM terms, which can offset high insurance costs.
Tap equity in a Louisiana rental without giving up a low-rate first mortgage.
Finance permitted short-term and mid-term rentals near festivals, LSU game days or Lake Charles projects using projected income.
Louisiana DSCR Loan FAQs
How much do I need to put down on a Louisiana DSCR loan?
Most DSCR programs require 20-25% down on a purchase. Select programs allow less with strong credit and a higher DSCR. Short-term rentals and properties with a DSCR under 1.0 usually need more down.
Do Louisiana DSCR loans have prepayment penalties?
They can. In Louisiana, prepayment penalties longer than one year generally must step down each year, such as 3-2-1 or 5-4-3-2-1. You can also choose a loan with no prepayment penalty.
Can I use Airbnb income to qualify in Louisiana?
Yes, on eligible programs, using booking history or a short-term rental market analysis. Check local rules first: New Orleans limits short-term rentals with a lottery and an on-site operator requirement in residential areas.
Can I close in my LLC?
Yes. DSCR loans can close in the name of an LLC or corporation, with the owners signing a personal guarantee.
Can I get Louisiana's homestead exemption on a rental property or one held in an LLC?
No. The homestead exemption ($7,500 of assessed value, about $75,000 of market value) applies only to a home the owner occupies as a primary residence. Property owned by a business entity such as an LLC or partnership, or used for business, does not qualify. A rental is therefore taxed on its full assessed value, which is 10% of fair market value for residential property.
Can I buy a house in New Orleans to use as a whole-home Airbnb?
Generally not in residential neighborhoods. New Orleans requires a permit for any rental under 30 days. Its non-commercial residential STR permit requires an operator who lives on site and allows only one per square, awarded by lottery, and in a single-family home one bedroom must be kept for the owner's full-time use. Whole-unit commercial STRs are limited to districts where zoning allows them, so check zoning and permit rules before buying a property for short-term rental income.
How much notice does a Louisiana landlord give before filing an eviction?
Louisiana generally requires a written notice giving the tenant at least five days to vacate. A lease can waive that notice in writing, so many Louisiana landlords include a waiver clause; have a Louisiana attorney review your lease.
How does flood insurance affect a Louisiana DSCR loan?
Flood insurance is required for properties in FEMA high-risk zones, and the premium is counted in the PITIA payment that sets your ratio. Checking the flood zone and asking for an elevation certificate before you offer helps you avoid surprises.
What is Louisiana's income tax on rental income?
For tax years starting in 2025, Louisiana taxes individual income at a flat 3%, including net rental income. A CPA can explain how depreciation and your entity structure affect what you owe.
Can I get a DSCR loan on a New Orleans condo?
Often, yes, as long as the building passes the lender's condo project review. Lenders look closely at the association's master insurance, reserves and any rental restrictions, so request the condo documents early.
Get a Louisiana DSCR Rate Quote
Tell us about the property and we'll shop multiple DSCR lenders so you can compare options. No credit check to see your options.
Check My EligibilityLooking for another state? See all DSCR loan states.
DSCR Loans Explained
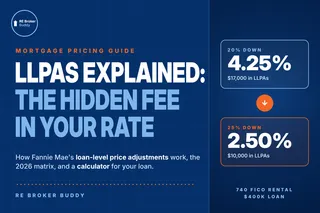
LLPA Explained: Fannie Mae's Loan-Level Price Adjustment Matrix (2026)
What a loan-level price adjustment (LLPA) is, how it works, the 2026 Fannie Mae LLPA matrix, investment property LLPAs, real-dollar examples and a calculator. ...more
DSCR loans ,Mortgage Market Updates
October 28, 2026
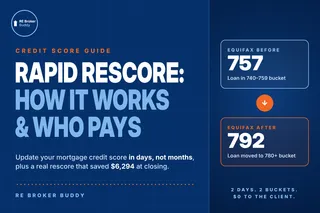
Rapid Rescore: How It Works, How Long It Takes and Who Pays
What a rapid rescore is, how it works, how long it takes, what it costs and who pays, what it can't fix, and a real rescore that saved $6,294 at closing. ...more
DSCR loans
October 28, 2026
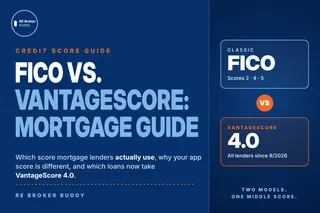
FICO vs. VantageScore for Mortgages: Which Credit Score Do Lenders Use?
Which credit score mortgage lenders use, how classic FICO and VantageScore 4.0 differ, why Credit Karma doesn't match your mortgage score, and which loans now accept VantageScore 4.0. ...more
DSCR loans ,Mortgage Market Updates
October 28, 2026
Where We Offer DSCR Loans
*Must Close in LLC
STEP 1
Apply Online or Call Directly
Find out how much home you can buy or discover how much you can save by refinancing.
STEP 2
Review What Options You Can Qualify For
Learn exactly how much you qualify for and what you would save by working with us.
STEP 3
Get Loan Approval in 24 Hours
Get mortgage loan approval to move forward with your property.



Broker Buddy LLC
Trevor Gravink
Mortgage Consultant
CEO/Owner
(619) 404-6637
NMLS: 1707407
NMLS Consumer Access Lookup Tool
CA DRE # 02117228
5371 Wilshire Dr. San Diego, CA 92116
© 2026 Broker Buddy LLC
Powered by Adaptive Mortgage Solutions
Company NMLS # 2022974
CA DRE # 02126109
